The semaglutide patent expiry of March 2026 has now had six months to work. The evidence is uneven. In India, prices fell by up to 70% within weeks. In Canada, generic pens reached pharmacies in May. In China, not one generic has been approved. Readers in the United Kingdom, the United States and the European Union should note one point above all. None of this applies to them. Protection in those markets runs to 2031 and beyond.
That gap between markets is the real story. It is also the most widely misunderstood part of it.
What the semaglutide patent expiry actually covered
Semaglutide is the active ingredient in Ozempic, Wegovy and Rybelsus. IQVIA ranked it the world’s second best-selling prescription medicine in 2024. Combined sales that year were $26bn, growing at roughly 40%. Full-year 2025 sales across Ozempic, Wegovy and Rybelsus came to about $36bn. That left the franchise behind Eli Lilly’s tirzepatide products.
The core compound patent expired in India and in China on 20 March 2026. It expired in Brazil during the same month. In Canada, a core patent had already been allowed to lapse rather than run its term.
GLP-1 uptake by country was already highly uneven before any of this. Research published in the journal Obesity in August 2026 set out the scale. Twelve countries reaching expiry in 2026 account for 47% of the global obesity burden. They also account for 49% of global type 2 diabetes. The authors estimated that generic injectable semaglutide could be produced for $28 to $140 per person each year. Oral formulations ranged from $186 to $380. Injection devices took a disproportionate share of that cost.
Semaglutide is only one molecule inside the much wider patent cliff facing big pharma. Nothing expired in the United States, the United Kingdom, the European Union or Japan.
British readers arriving at this subject from search should be clear on the position. No generic semaglutide is available in the UK. Novo Nordisk retains exclusivity here, and the products reaching the market remain its own. The company launched the oral Wegovy pill in the UK in July 2026. It had already introduced the 7.2mg single-dose pen in June. Cheaper UK supply will not arrive through the semaglutide patent expiry for several years.
Why the semaglutide patent expiry dates differ by country
The mechanism is straightforward. A patent runs for 20 years from its filing date. The PCT application covering semaglutide, WO2006/097537, was filed in early 2006. Jurisdictions without an extension mechanism therefore reached the end of that term in early 2026.
Europe, the United States and Japan all operate extension mechanisms. In Europe the instrument is the supplementary protection certificate, or SPC. It compensates an innovator for years lost to regulatory review. Its length is the period between patent filing and first marketing authorisation, minus five years. The extension is capped at five years.
European loss of exclusivity is consequently expected in 2031. In the United States, patent term extension should hold protection until at least 2032. Japan falls near 2031.
This is why one molecule can be a commodity in Mumbai and a protected brand in Manchester. The difference is legal architecture, not chemistry. It is also why the semaglutide patent expiry should never be described as a single global event.
India: forty brands and a price collapse
India moved fastest, confirming its place among the new pharma powerhouses. Sun Pharma, Dr Reddy’s Laboratories, Zydus Lifesciences and Lupin launched on 21 March, the day after expiry. More than 40 companies had prepared versions.
Reuters reported that Indian generics undercut Novo Nordisk by up to 70% in some cases. Novo responded on 31 March with its second cut since November. It reduced Ozempic by up to 36% and Wegovy by up to 48%. The 0.25mg weekly dose of each fell to 1,415 rupees, roughly $15 at the rate reported at the time. Average reductions across doses were 23.8% for Ozempic and 27% for Wegovy.
“We’ve heard from patients and doctors, and we’re acting on that feedback,” said Vikrant Shrotriya. He is managing director at Novo Nordisk India.
Reported generic pricing has since settled across a wide band. Indian market coverage has put entry-level vial products near 1,290 rupees a month. Pen-based products have been reported at roughly 4,200 rupees. Those figures come from market coverage rather than audited data, and should be read as reported rather than verified. Branded prices before expiry ran far higher.
The run-up was litigated. On 2 December 2025, the Delhi High Court refused Novo Nordisk an interim injunction against Dr Reddy’s. The court allowed manufacture and export to countries without patent protection. Domestic Indian sales stayed barred until the patent lapsed in March. Novo Nordisk appealed. A division bench reserved judgment on 19 January 2026 and dismissed the appeal on 9 March. That was eleven days before the patent expired. The bench held that semaglutide was prima facie obvious over Novo Nordisk’s own earlier genus patent.
Canada became the first G7 market to open
Canada produced the most consequential regulatory moment of the semaglutide patent expiry. On 28 April 2026, Health Canada authorised a generic semaglutide injection from Dr Reddy’s Laboratories. It was the first such approval by a G7 regulator. Apotex followed on 1 May and launched commercially on 14 May.
On 29 June, Health Canada cleared the first generic indicated for weight management. That product is an Apotex version of Wegovy. Six further submissions were under review at that point.
Health Canada described the products carefully. Generic semaglutide, it said, comprises complex synthetic products that are pharmaceutically equivalent to the brand name biologic drug. The terminology matters. These products do not follow the same regulatory route as the biosimilar approvals seen elsewhere in the sector. The category assigned to copies of semaglutide differs between jurisdictions. “Biosimilar” is not universally correct.
Novo Nordisk confirmed the commercial effect in its half-year report. In Canada, it stated, loss of exclusivity has lowered realised prices. Its own volumes have held broadly stable.
Reimbursement has moved with the market. Ontario listed the generics on its drug benefit formulary on 30 June 2026. The listed benefit price for an Ozempic pen is C$227.94. With interchangeable generics now listed, the ministry reimburses at the generic price of C$78.14. Those figures come from Canadian market coverage rather than a formulary extract.
China and Brazil have diverged sharply
Brazil has opened in stages. EMS secured ANVISA approval in May for Ozivy, its own synthetic semaglutide pen. Brazilian coverage has since reported Ozivy on sale at around 333 reais through the company’s loyalty programme. ANVISA registered Brazil’s first true generic semaglutide, also from EMS, on 17 August 2026. No launch date or price has been announced for it.
Sandoz obtained authorisation for Owozy, a product developed with Adalvo. Sun Pharma received ANVISA clearance in July. It moved to launch through a partnership with Hypera Pharma. Sun cited IQVIA data valuing Brazil’s injectable semaglutide market at about $413m for the twelve months to June 2026.
China has not opened, and the reason is instructive. At least ten domestic manufacturers filed for approval. None has been granted. The obstacle is not patent law but regulatory data protection.
Novo Nordisk’s Chinese marketing authorisation is held by its Swiss subsidiary. Under the China to Switzerland free trade agreement, that entitles Ozempic to data protection until April 2027. Novo confirmed this position in May 2026. Applicants including Hangzhou Jiuyuan Genetic Biopharmaceutical have reported that their reviews are suspended on those grounds.
Turkey is routinely grouped with the 2026 cohort by IQVIA and by the Obesity analysis. No confirmed commercial launch there has been identified.
The lesson generalises. The semaglutide patent expiry established freedom to operate. It did not deliver a marketing authorisation, a device, or a supply chain.
The secondary patent battleground
Core patents were never the whole portfolio. Novo Nordisk holds extensive secondary rights. These cover formulations, dosing regimens, indications and injection devices.
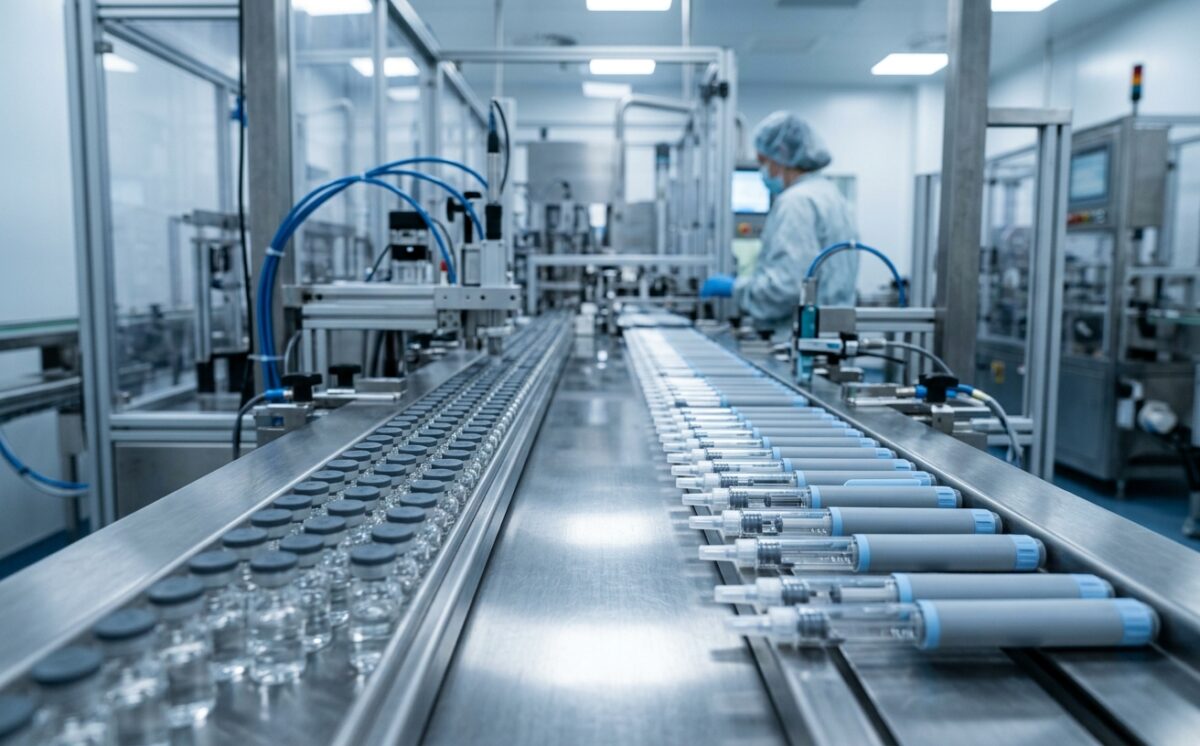
Device patents bite selectively. They constrain only competitors that also intend to copy the delivery system. That is one reason several early Indian entrants appeared in vials as well as pens. The choice is not only legal. The Obesity analysis found that the injector device drives a large share of unit cost. A vial can therefore be markedly cheaper to supply than a pen. A second common route is the skinny label. Under it, a generic is approved only for indications that remain unpatented.
Litigation is running in parallel. European Patent Office Boards of Appeal revoked EP2827845, EP2827885 and EP2866825. EP3746111 and EP3870213 were upheld at first instance. In October 2025, Novo Nordisk obtained 26 ex parte preliminary injunctions in Germany over EP1863839. They were served at the CPHI trade fair in Frankfurt.
The pressure has now reached the highest-value markets. On 30 June 2026, Sandoz filed for revocation of Novo Nordisk’s unitary patent EP3689365. The action was brought at the Unified Patent Court in Milan. That patent covers the 1mg dose of semaglutide for diabetes across 18 EU states. Separately, Cipla has filed an abbreviated new drug application in the United States. It carries paragraph IV certifications, and Novo Nordisk has sued for infringement in New Jersey.
Apotex is the other US front. It holds a tentative FDA approval for its own generic semaglutide, granted in April 2026. Novo Nordisk’s three US suits against Apotex, covering Rybelsus, Ozempic and Wegovy, were consolidated in June 2026.
What the semaglutide patent expiry means for Novo Nordisk
The exposure is real but not yet decisive. Novo Nordisk raised its 2026 outlook on 4 August. It guided to adjusted sales growth of 0% to minus 6% at constant exchange rates. That improved on the minus 4% to minus 12% range issued in May. The company attributed the upgrade mainly to stronger GLP-1 sales.
Its outlook statement names the compound patent expiry of semaglutide in certain markets as a headwind. Lower realised prices in the United States sit alongside it. Yet obesity care sales in International Operations still grew 37% at constant exchange rates in the second quarter.
The strategic response is visible in the portfolio rather than the litigation. Novo has pushed the oral Wegovy pill into new markets through 2026. It has also rolled out the 7.2mg high-dose pen and continues to advance CagriSema. In the REIMAGINE 4 head-to-head trial, CagriSema matched tirzepatide on weight loss but not on HbA1c. A US decision is expected in the fourth quarter of 2026. Scaling oral GLP-1 manufacturing is its own supply test. Those products carry fresh exclusivity that semaglutide no longer enjoys everywhere.
The corporate framing is changing too. On 14 September 2026 the company adopted “Novo” as its day-to-day name, with Novo Nordisk A/S remaining the legal entity. A Capital Markets Day on 21 September in London is due to set out the updated strategy in full.
For the markets that opened this year, the constraint is shifting from law to logistics. Devices, cold chain, reimbursement and prescriber capacity now determine how far cheaper semaglutide travels. The semaglutide patent expiry has answered the legal question. The access question remains open.